

MoneyGram® Money Transfers App
by MGI
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
I use money-transfer apps when the important thing is getting funds moving without turning the process into a long visit to a branch. MoneyGram® Money Transfers App takes that familiar service and puts the main workflow on a phone: choose where the money is going, enter the recipient details, select a delivery method where available, and follow the transfer through its progress. It is a finance app from MGI, aimed at international transfers rather than everyday budgeting or banking.
That focus is both its biggest strength and its first important boundary. I would recommend it to someone who regularly sends money abroad, supports relatives in another country, or needs a recognizable transfer service while traveling. I would not choose it as a replacement for a full bank app, a personal finance tracker, or a tool for comparing every possible exchange option. It is built around sending money, and the experience makes the most sense when that is the task I need to complete.
How the everyday transfer workflow feels
I find the everyday transfer workflow easiest to manage when I decide the recipient’s preferred way to receive the money before opening the app. That small step helps me judge the available route by what will work for them, not just by what looks quickest on my screen. I’ll also look at how a clear review-and-confirm routine can prevent avoidable snags.
Starting with the recipient, not the app menu
My preferred way to use the app is to prepare the recipient information before opening the transfer form. Having the person’s name exactly as it appears on their identification, along with the destination country and the details required for the chosen delivery method, reduces the chance of stopping halfway through. This is especially useful when I am sending money to someone who is waiting for it and cannot easily answer follow-up questions.
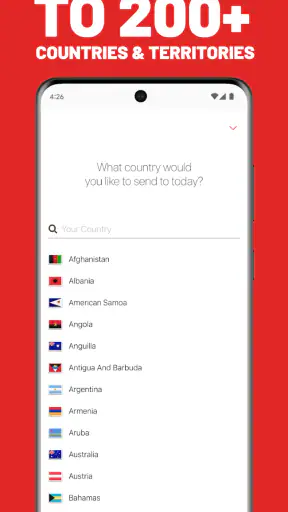
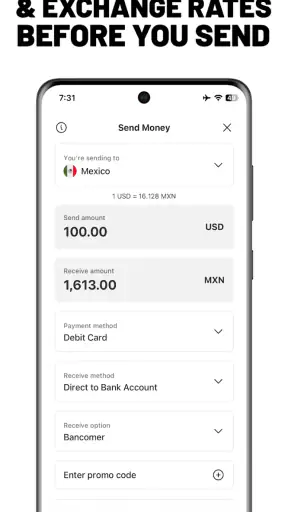
The initial workflow is straightforward: I identify the destination, enter the amount, review the available delivery choices, and check the transfer summary before continuing. That final review deserves more attention than it usually gets. I look at the amount the recipient should receive, the total I am being asked to pay, the delivery method, and the spelling of the recipient’s name. A small error in a name can create more trouble than a slow screen ever will.
The app’s store summary describes its purpose clearly: it supports global currency, money, and wire transfers abroad online. In practice, I see it as a guided transaction rather than a financial dashboard. It does not try to distract me with charts, spending categories, or investment tools. When I open it, the useful question is simply whether I can set up and manage the transfer I came to make.
What I check before confirming
I never treat the first amount shown as the whole cost. A transfer can involve the amount sent, the amount received, the exchange rate, and any applicable charges, so I read the complete review screen instead of judging the transaction from one prominent number. This habit is more valuable than trying to memorize a single “best” route, because the practical value can change with the destination and delivery option.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I also check whether the recipient needs a bank deposit, another supported delivery route, or an in-person collection option. The right choice depends on the recipient’s circumstances. Someone with reliable access to a bank account may prefer a direct deposit, while someone who needs cash may value a pickup route even if it requires a trip. The app is most helpful when I decide this with the recipient first, rather than selecting the fastest-looking option automatically.
For a realistic example, imagine that a family member abroad needs money for an urgent household expense. I would first message them to confirm the exact name and how they can receive the funds. Then I would use the app to compare the available delivery choices, review the total, and save the confirmation details. That sequence avoids the common mistake of starting with an amount and discovering later that the recipient cannot use the selected method.
Tracking is part of the workflow
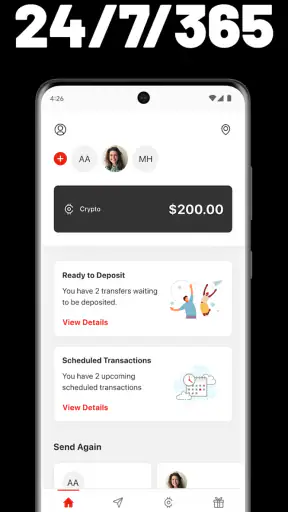
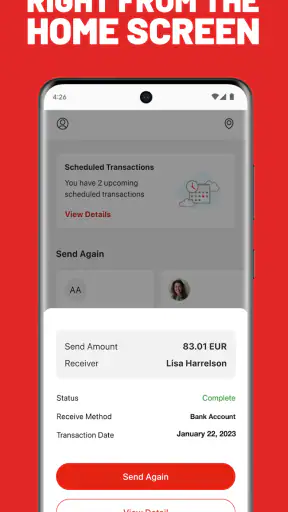
Sending the money is not the end of the job. I keep the transaction information available and use the app’s tracking path when I need to understand where the transfer stands. I also tell the recipient what information they may need, depending on the delivery method. This is a small but important distinction: the sender may see progress in the app, while the recipient may still need identification or transaction details to complete collection.
I avoid promising an exact arrival time based only on my own expectation. Delivery can depend on the route, destination, verification steps, operating hours, and the receiving institution or location. The app makes the transfer easier to organize, but it cannot remove every condition outside the phone. If the money is urgent, I start early enough to allow room for a review or correction instead of waiting until the last possible moment.
Settings and account habits worth checking
Experienced use is less about discovering a secret button and more about making the visible process repeatable. I check my profile and contact information before sending a meaningful transfer, keep the recipient’s details in a secure place, and avoid relying on memory for names or account information. I also make sure I am using the current version available for my device. The current version is 26.7.21, and the app supports Android 8.0 or later, which matters if I am using an older phone for travel or family assistance.
I treat notifications as useful reminders rather than proof that a transfer is complete. A message that a transaction has changed status is a prompt to open the app and read the actual details. This habit prevents me from forwarding an incomplete update to the recipient or assuming that a pending transaction has already become available.
Security habits matter more here than cosmetic customization. I use a private connection when handling financial information, keep the phone protected, and avoid entering details while someone else can easily see the screen. I also verify the recipient through a separate conversation before confirming a transfer. These steps are not flashy app features, but they are the settings-and-routine combination that makes a finance tool safer to use in real life.
The age rating is Everyone, which makes the app broadly approachable from a store perspective, but that should not be confused with a transaction being suitable for every situation. Money transfers involve personal and financial information. I would still supervise how a younger person uses it and make sure the account holder understands the payment and recipient details before anything is sent.
Shortcuts that actually save time
My most useful shortcut is preparing recurring transfers outside the final payment step. I keep a private note with the recipient’s exact legal name, destination, preferred delivery route, and any information I need to check before sending. I do not copy blindly; I compare it with the current request each time. This gives me the speed of a template without turning an old detail into a permanent mistake.
A second shortcut is separating “amount planning” from “transfer execution.” I first decide how much the recipient should receive, then use the app to see what I would need to pay. If I begin with the amount leaving my account, I can lose sight of the person’s actual need after exchange-rate and cost details appear. Thinking from the recipient backward makes the final review clearer.
For repeat users, I recommend making a small checklist and following it in the same order: recipient identity, destination, delivery method, recipient amount, total cost, and confirmation. It takes only a moment once familiar, yet it catches the errors that are hardest to fix. This is more dependable than rushing through a familiar screen because the process feels routine.
I also capture the confirmation in a secure place and send only the necessary reference information to the recipient. I do not share screenshots containing unrelated personal details. A clean, limited message is easier for the recipient to use and reduces the amount of sensitive information moving through ordinary chat.
Where it compares well with usual alternatives
Compared with visiting a traditional money-transfer location, the app is more convenient when I already have the required information and a suitable payment method. I can begin the process from home, review the transaction before committing, and keep the transfer history in the same place. That is particularly useful for people who send money outside normal opening hours or who live far from a physical location.
Compared with a bank’s international-transfer feature, MoneyGram has a different emphasis. A bank app may be the more natural choice when both sides already use compatible bank accounts and the transfer is part of regular account management. MoneyGram is more appealing when the recipient needs one of the delivery options associated with its transfer network or when I want a service centered specifically on sending money internationally.
Compared with newer digital remittance services, the decision is not just about a clean interface. I would compare the complete cost, exchange result, delivery route, recipient convenience, and the level of support available in the destination. A different app may be better for someone who values a particular bank corridor or specializes in low-cost account-to-account transfers. MoneyGram can be the better practical fit when the recipient’s access and collection options matter more than having the smallest-looking fee.
Limits and moments when I would choose something else
The app cannot make an unsuitable recipient route suitable. If the person receiving the money has no access to the selected account, location, or identification needed for collection, a polished mobile process will not solve the problem. I always ask the recipient how they want to receive the funds before I start, especially when they are in a different country and I cannot help them in person.
I also would not use it for ordinary spending analysis. There is no reason to open a transfer-focused tool when what I really need is a budget, bill calendar, card-management system, or a record of household expenses. Likewise, if I am making a large or unusually sensitive transfer, I take extra time to verify every detail and consider whether my bank or another regulated option better matches the situation.
Exchange rates and charges deserve a realistic attitude. The most convenient route is not automatically the least expensive, and the lowest visible fee does not necessarily produce the highest amount received. I compare the final recipient amount and total payment rather than focusing on one line. If the difference matters, I check another legitimate option before confirming instead of assuming that speed alone represents value.
There can also be friction when information needs correcting. Recipient names, destination details, and delivery choices are not casual fields. I therefore treat the review screen as a decision point, not a formality. If anything looks wrong, I stop and resolve it before paying. That slower moment is preferable to discovering an error after the transfer has entered processing.
What the adoption numbers suggest, and what they do not
The app has a 4.6 average from around 128 thousand ratings and has passed 5 million installs. Those figures tell me that it is an established choice rather than an obscure experiment, and the substantial review volume gives prospective users a useful sense that many people have tried it. They do not remove the need to check whether the service fits a particular destination, recipient, or transfer method.
MoneyGram has been available since May 13, 2014, and MGI continues to develop the app. That long presence helps explain why I view it as a practical service with a recognizable transfer workflow, not merely a temporary mobile interface. Still, experience with the brand should not replace careful reading of each transaction. Conditions can differ from one transfer to the next.
Who should use it
I think it is a strong match for people who send international support payments, travelers who need a remote way to arrange a transfer, and families who already understand which receiving option works for their relative. It is also useful for someone who prefers completing the setup digitally but wants the recipient to have a delivery choice that is not limited to the sender’s bank ecosystem.
I would be more cautious recommending it to someone who sends money only occasionally and is uncomfortable checking recipient information, exchange details, or transaction status. The app makes the process accessible, but it does not make financial responsibility optional. A first-time user should ask the recipient what they need and read every summary screen rather than assuming the default path is correct.
My verdict after building a repeatable routine
After using it as a focused transfer tool, I see MoneyGram® Money Transfers App as a practical choice for international money movement, especially when recipient convenience is as important as sender convenience. It is free to install, and the Everyone rating makes it easy to approach, but the real value comes from using it carefully: prepare the recipient details, compare the complete cost, choose the delivery route with the recipient, and keep the confirmation information organized.
My strongest recommendation is to make the process boring and consistent. Use the same checklist, verify the name every time, treat notifications as status prompts, and never confuse a familiar recipient with a permanently correct set of details. Those habits make the app faster without encouraging careless taps.
The best reason to choose this app is control over a clearly defined transfer workflow, not the promise of effortless finance. If that is what I need, it earns a place on my phone. If I want budgeting, broad banking, or the absolute best option for every exchange corridor, I would look elsewhere. For sending money abroad with a recognizable, mobile-first process, however, it is a sensible tool that rewards a little preparation.
Pros
- Send money internationally from your phone without visiting a branch.
- Multiple delivery options include bank accounts, cards, and cash pickup.
- Transfer tracking helps you monitor the payment status in real time.
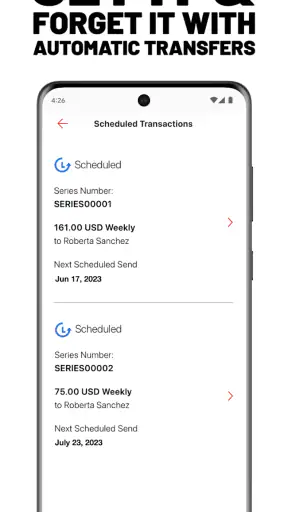
- Supports recurring transfers for users who send money regularly.
- Biometric login adds a convenient layer of account security.
Cons
- Fees and exchange rates can vary significantly by destination and payment method.
- Some transfers may require identity checks or additional documentation.
- Cash pickup availability depends on local agents and their opening hours.
- Transfer limits may restrict larger payments or frequent transactions.
- App features and supported services differ between countries.
FAQs for MoneyGram® Money Transfers App
What can I do with the MoneyGram® Money Transfers app?
The MoneyGram® Money Transfers app is designed to let you send money internationally or domestically from your mobile device. Depending on the destination and local availability, you can choose delivery to a bank account, mobile wallet, debit card, or a participating MoneyGram location for cash pickup. The app also provides transfer tracking, recipient details, estimated delivery information, and access to your transaction history.
How much does it cost to send money with MoneyGram?
Transfer costs are not fixed and can vary according to the amount, sending country, destination, payment method, delivery option, and current exchange rate. Before confirming a transaction, the app normally displays the transfer fee, exchange rate, recipient amount, and total cost. It is worth comparing these details carefully, because paying with a card or choosing cash pickup may cost more than other available options.
What information do I need to send money through the app?
You generally need to create or access a MoneyGram account and provide accurate personal information, such as your legal name, contact details, and identity verification documents when requested. You will also need the recipient’s full name and delivery information. Requirements can differ by country, transfer amount, and payment method, so checking every spelling and account detail before submitting the transfer is essential.
How long does a MoneyGram transfer take, and can I track it?
Delivery time depends on the destination, selected payout method, payment method, operating hours, compliance checks, and possible holidays or technical delays. Some transfers may arrive quickly, while bank deposits and certain international transactions can take longer. After sending money, you can usually track the transaction in the app with the reference number or through the transfer history, where available status updates are shown.
Is the MoneyGram app safe, and what should I do if there is a problem?
MoneyGram uses account security measures and transaction verification procedures, but users should still protect their login credentials, avoid sharing verification codes, and use only the official app from a trusted store. Review the recipient and total cost before confirming, because completed transfers may be difficult to reverse. If a transfer is delayed, incorrect, or suspected to be fraudulent, contact MoneyGram support promptly through the official help channels.

MoneyGram® Money Transfers App
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via customerservice@moneygram.com, visit https://www.moneygram.com, or review their http://global.moneygram.com/privacy-notice.










